Individualised Altersvorsorgedepots
One account per customer instead of an off-the-shelf model portfolio, built from profile, preferences and horizon. The partner configures the investment concept and documents, under its own brand.
The state-subsidised pension account created by the German pension reform act, a securities account, not an insurance wrapper.
One account per customer instead of an off-the-shelf model portfolio, built from profile, preferences and horizon. The partner configures the investment concept and documents, under its own brand.
Fund costs from 0.05% in AVD Standard, Premium building blocks from 0.09% to 0.11% including active ETFs. One cost line per year, with no hidden transaction or entry charges.
No lock-in to individual asset managers: the investment concept decides which building blocks go into a portfolio, ETFs and actively managed funds side by side. The private-markets booster for AVD Premium is already being built.
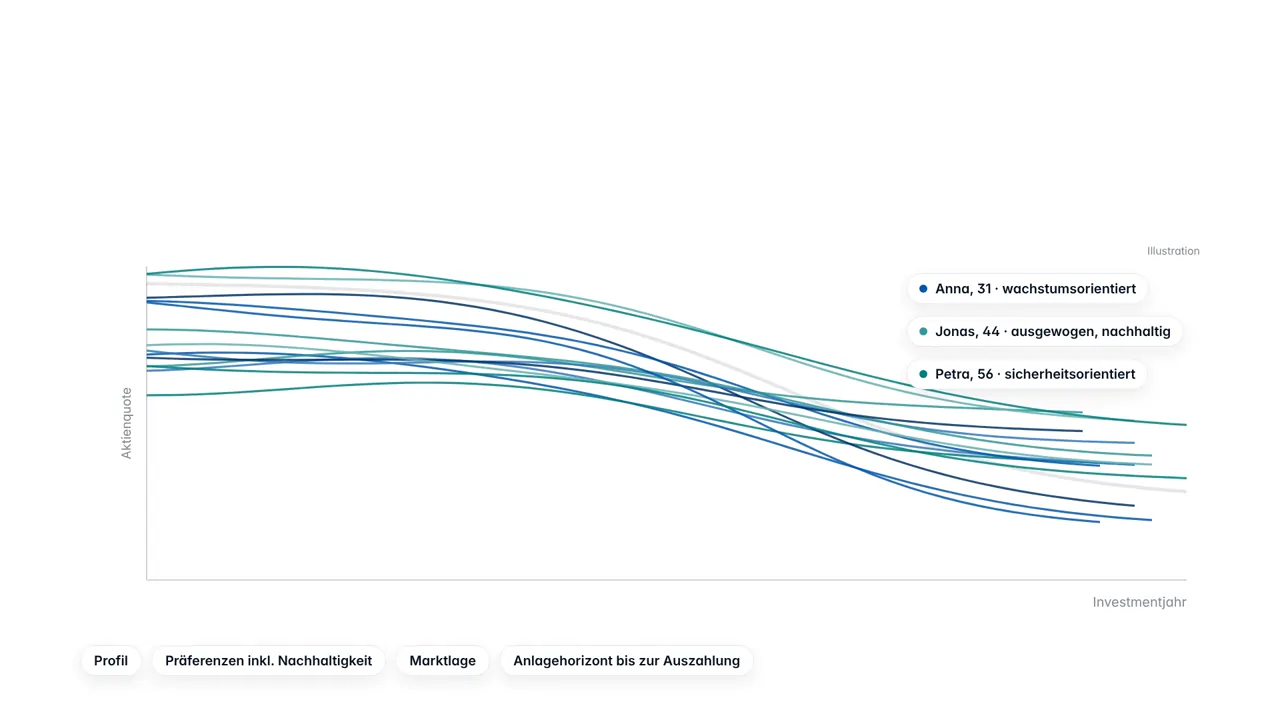
Lifecycling per customer, not per cohort: suitability selects the glide path, the remaining horizon the position on it. Risk steps down year by year, with the statutory de-risking caps built in.
An annuity, a payout plan to at least 85 or up to 30% as a lump sum at the start, under the rules of the pension reform act. Capital needs, payout duration, inheritance and gifts shape the plan.
Sources: Xaver product conditions, 2026 (fund costs) · BMF FAQ on the private pension reform, 2026 (payout rules)
How we invest: An asset management platform of Xaver Asset Management GmbH, supervised by BaFin, built on low-cost instruments and a lifecycle-driven allocation framework. Asset management infrastructure →
Four title cards and seven scenes from the platform animation: what changes with the Altersvorsorgedepot, and what partners get from Xaver, from pre-registration to operations. Altersvorsorgedepot as a Service →
The AVD family has four lines: AVD Standard, the statutory standard account, managed, with a lifecycle in eleven allocation steps and fund costs from 0.05%; AVD Premium as active discretionary management with lifecycling per customer rather than per cohort and building blocks from 0.09% to 0.11% including active ETFs; AVD Garantie with guarantee options through partner insurers; and the Nettotarif, available through our partners from January 2027.
| Line | AVD StandardFrom 1 January 2027 | AVD PremiumFrom 1 January 2027 | AVD Garantie (guarantee)Through partner insurers | Nettotarif (net tariff)From January 2027 |
|---|---|---|---|---|
| Completable in the same journey | Yes | Yes | Yes | Yes |
| Investment | The statutory standard account, managed: lifecycle in eleven allocation steps, fund costs from 0.05%. | Active discretionary management, lifecycling per customer rather than per cohort; building blocks from 0.09% to 0.11% including active ETFs; example path “Secure”. | Guarantee options through partner insurers; the partner sets the guarantee level and term. | Investment concept as configured; remuneration through a fee agreement rather than commission. |
| Advice & suitability | The statutory Standarddepot with Xaver's portfolio management (DPM overlay); suitability assessment and documentation inside the journey. | Full advice with a suitability statement, documented inside the journey. | Full advice with a suitability statement; the guarantee is part of the suitability assessment. | Full advice with a suitability statement; the partner agrees the fee with the customer. |
| Configurable by the partner | Investment concept and documents; cost structure within the statutory frame. | Investment concept, costs and documents, all under your brand. | Guarantee level and term, investment concept and documents. | Investment concept and documents; remuneration sits in the fee agreement. |
| Subsidy | Allowances and the special-expenses deduction under the AVRG. | Allowances and the special-expenses deduction under the AVRG. | Allowances and the special-expenses deduction under the AVRG. | Allowances and the special-expenses deduction under the AVRG. |
| Responsibility: product · advice · custody · servicing | Product and custody: Xaver with the partner banks. Portfolio management: Xaver. Servicing: Xaver, under your brand. | Product, custody and servicing: Xaver. Advice: your house, supported by the journey and the co-pilot. | Product including the guarantor: Xaver with the partner insurer. Advice: your house. Custody and servicing: Xaver. | Product, custody and servicing: Xaver. Advice and the fee agreement: your house. |
| Status | Pre-registration from October 2026, product launch 1 January 2027. | Pre-registration from October 2026, product launch 1 January 2027. | Through partner insurers, from 2027. | Available through our partners from January 2027. |
Entry before the cut-off date: the AVD Bridging Product comes in two versions. The money-market version invests in a low-volatility EUR money-market fund, the invested version implements the allocation of the later AVD line ahead of launch. The Bridging Product is not itself an AVD product, carries no subsidy while it is held, and the transfer from January 2027 is not automatic. Money-market funds are not deposits; the invested version carries full market risk from day one.
AVD Garantie: the guarantee is a contractual product feature of the partner insurer, which undertakes to make at least the agreed amount available at the agreed date. It is not a statement about performance.
Next development: the private-markets booster as a building block for AVD Premium, already being built.
No children entered.
Exactly the minimum own contribution, allowances are paid in full and nothing beyond that is contributed.
The same own contribution as the Riester variant, bounded by €120 and €1,800.
Riester pension
30.32%
Gross contribution €1,920
Altersvorsorgedepot
30.26%
Gross contribution €2,271
The subsidy ratio of the old system (Riester) is virtually identical to the subsidy ratio of the new system (Altersvorsorgedepot).
The subsidy is the sum of allowances and tax relief. It is set against the gross contribution, so the subsidy ratio shows what share of the gross contribution the state carries.
The link carries only the calculator inputs, no personal data. The card is the result as an image (1200 × 630 px).
| Item (p.a.) | Riester | Altersvorsorgedepot |
|---|---|---|
| Own contribution | €1,745.00 | €1,745.00 |
| ·Basic allowance | €175.00 | €526.25 |
| ·Child allowance | €0.00 | €0.00 |
| Allowances, total | €175.00 | €526.25 |
| Tax relief (after the more-favourable test) | €407.23 | €161.12 |
| Net outlay | €1,337.77 | €1,583.88 |
| Gross contribution | €1,920.00 | €2,271.25 |
| Subsidy ratio | 30.32% | 30.26% |
The more-favourable test under § 10a of the German Income Tax Act: the special-expenses deduction only bites to the extent that it exceeds the allowances. A €0 figure means the allowances are already the better outcome.
Riester pension
Altersvorsorgedepot
Taxable income used in the calculation: €37,058 · single-assessment tariff
An example calculation, it does not replace advice. A non-binding model calculation. Results may differ depending on your individual tax and social-insurance position, which is not assessed here. This is not tax or investment advice.
Source: Calculated under the German pension reform act (Altersvorsorgereformgesetz, AVRG), in force from 1 January 2027. Legal position: income tax 2026, social insurance 1 July 2026.
Helvetia and BCA have been live with pre-registration since October 2026, with contracts from 1 January 2027.
Self-service or with an adviser, on the same data.
AI adviser guides and explains the recommendationNo second data capture, no system switch.
Pre-registration, not an application: no commitment, no payment obligation; confirm, change or leave it in January.