The reinvestment family covers what happens after maturity: flexible withdrawal planning, professionally managed reinvestment and a structured transfer of wealth. It is triggered by a maturing policy, a payout, an inheritance or a liquidity event.
Variations
Two components work together: liquidity and drawdown, family and estate planning.
Divestment
Available today
Structured withdrawal and retirement-income planning with professionally managed remaining assets. The risk profile falls as the horizon shortens.
Conservative multi-asset sleeve
Cash-flow oriented payout mechanics
Regular reviews with the adviser
Reinvestment / wealth transfer
Available today
Reinvestment after an inheritance, a sale or a payout, with a managed account and insurance structures for long-term family planning.
Managed-account share for liquidity
Insurance wrapper for generational transfer
Support from adviser and family office
Costs comprise investment management plus, for the insurance-based sleeve, a partner-dependent wrapper charge. Investment pricing tiers at larger volumes. The specific terms are disclosed during the commercial conversation.
Maturity management
When a policy matures, a conversation starts, not a letter.
A policy maturesThe maturity letter states an amount and a date, nothing more. In the journey, maturity becomes the reason for a conversation: the contract data is known, the options sit side by side, and the customer decides before the money lands uninvested in a current account.
Four options, open-endedPayout, reinvestment in an account, a payout plan or an annuity, in combination too. Which one fits depends on capital needs, payout duration, inheritance and gifts. The comparison shows every option with its consequences for access, risk and tax, and it is allowed to end with the payout.
Advice and record inside the journeyAdvice runs in the same journey that completes the case: self-service, adviser-assisted or in person. Suitability check and advice record are produced inside the process; what was recommended and why is there as a document before the customer decides.
Planned withdrawals and giftsA withdrawal in two years, a gift to a granddaughter on a fixed date, a beneficiary in the event of death: that sits in the plan, not in a note. The payout plan calculates with it, and the adviser sees it at the next conversation.
The four options
Payout: the maturity value to the current account, in full or in part
Reinvestment in an account: a managed portfolio with a risk profile that falls as the horizon shortens
Payout plan: a scheduled monthly withdrawal from the account, the remaining capital stays accessible and inheritable
Annuity: a lifelong pension through an insurer, without access to the capital
Which option fits is calculated inside the journey from the customer's own data, with visible assumptions and as a model calculation, not a promise. Example figures therefore belong in the conversation, not on this page.
The principle in motion
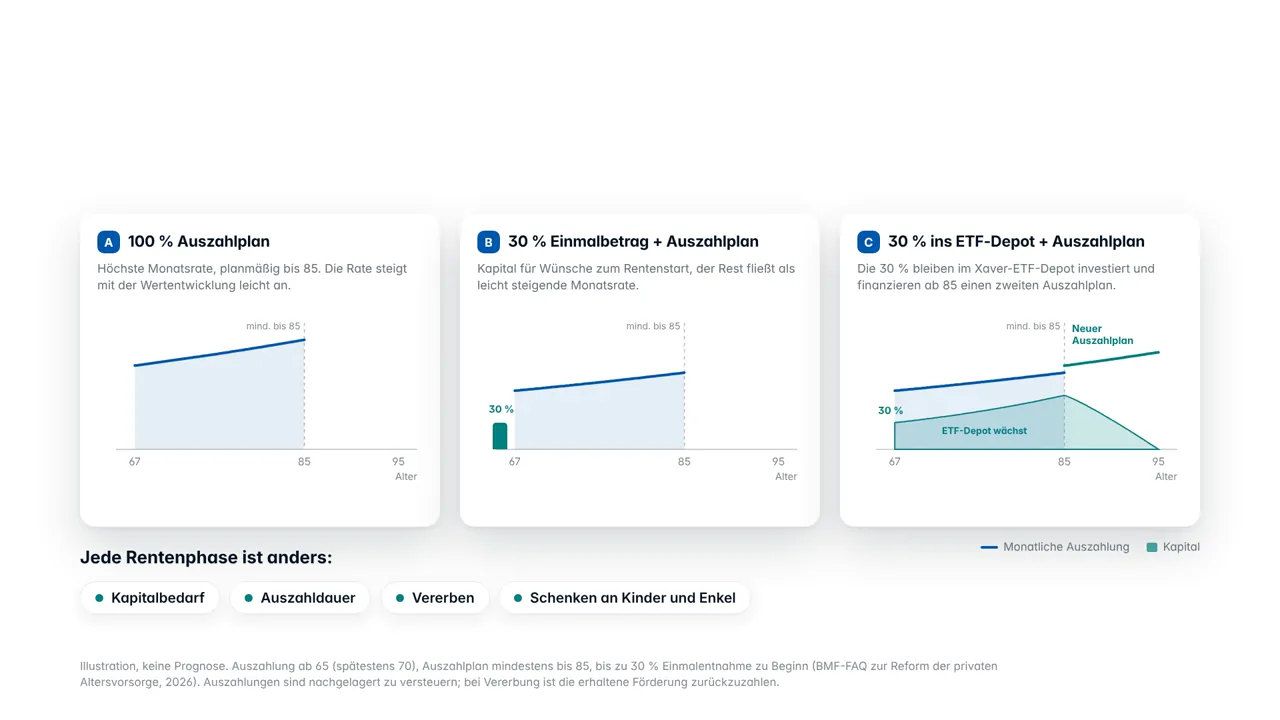
Three ways through the payout phase.
Illustration, not a forecast
01Payout phase, flexible
The Altersvorsorgedepot has fixed payout rules: payout from 65 (at the latest 70), a payout plan at least to 85, up to 30% as a lump sum at the start. Payouts are taxed on receipt; on inheritance the subsidy received has to be repaid. Source: BMF FAQ on the private pension reform, 2026. Illustration, not a forecast.
Demo · life insurer, workshop October 2026
A voice adviser for maturing policies
For a life insurer we built a voice adviser as a demo in October 2026: it talks to customers whose policy is about to mature, explains the options, sends a personal link to a page with their figures and walks them through it step by step, through to a payout plan with a planned withdrawal and a gift, or to a video appointment with the adviser, booked in the real calendar. A demo with fictional data under the insurer's brand; advice and record run inside the journey.